If you’ve ever searched for ways to grow your money, you’ve probably come across two terms again and again: SIP and mutual fund.
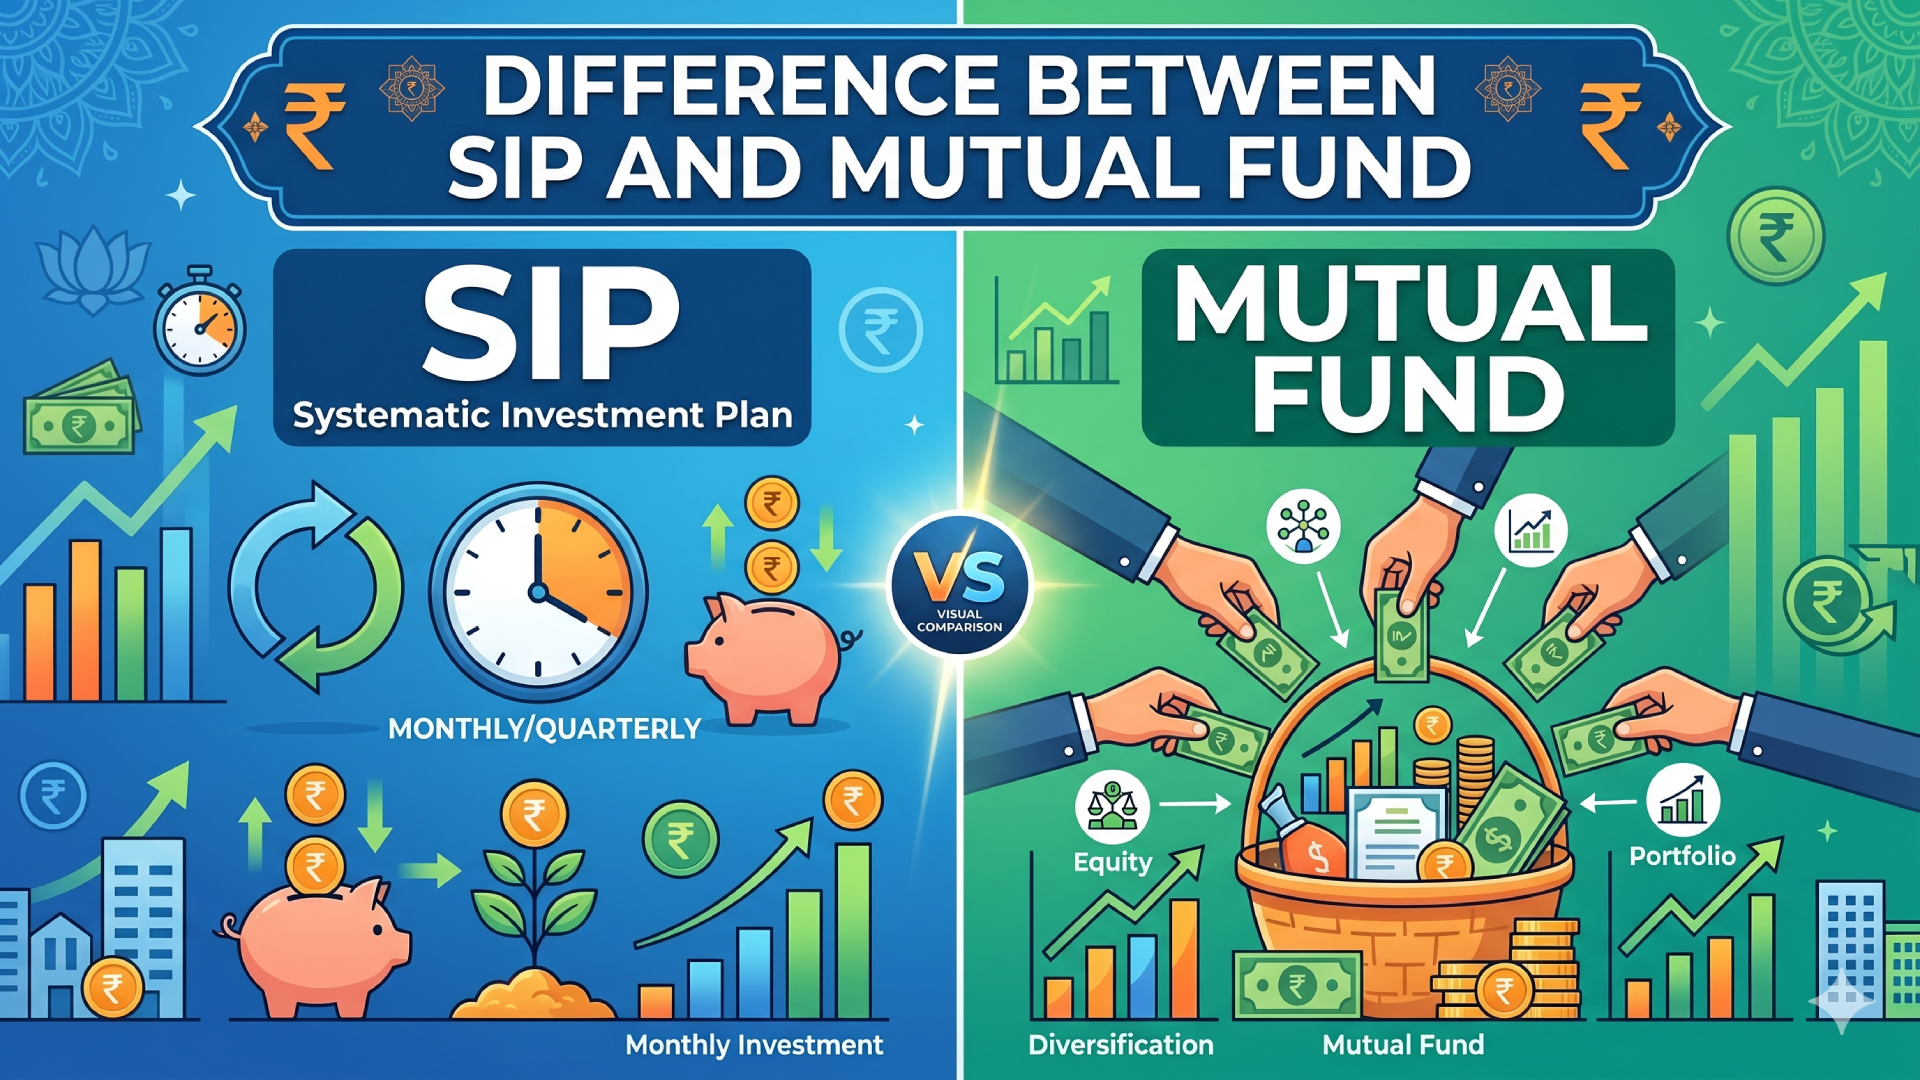
In this guide, you’ll learn the real difference between SIP and mutual fund, how each works, when to use them, and which option suits your financial goals. No fluff. No myths. Just clear, fact-based explanation.
What Is a Mutual Fund?
A mutual fund is an investment vehicle. It pools money from many investors and invests it in assets like:
- Stocks (equity funds)
- Bonds (debt funds)
- Gold or commodities
- Hybrid combinations
A professional fund manager handles the investments. The goal depends on the type of fund—growth, income, or stability.
How Mutual Funds Work
When you invest in a mutual fund:
- You buy units of the fund
- The value of each unit is called NAV (Net Asset Value)
- Your returns depend on how the underlying assets perform
Example
If you invest ₹10,000 in a mutual fund with NAV ₹50:
- You get 200 units
- If NAV rises to ₹60, your investment becomes ₹12,000
Simple.
What Is SIP (Systematic Investment Plan)?
A SIP (Systematic Investment Plan) is not an investment product. It is a method of investing in mutual funds.
With SIP, you invest a fixed amount regularly (monthly, weekly, or quarterly).
How SIP Works
Instead of investing a large lump sum, you:
- Invest small amounts periodically
- Buy mutual fund units at different NAVs
- Benefit from market fluctuations
Example
You invest ₹5,000 every month:
- Month 1: NAV ₹50 → 100 units
- Month 2: NAV ₹40 → 125 units
- Month 3: NAV ₹60 → 83 units
Over time, your average cost reduces. This concept is called rupee cost averaging.
Key Insight:
You don’t choose SIP vs mutual fund.
You choose SIP in a mutual fund or lump sum in a mutual fund.
SIP vs Lump Sum Investment in Mutual Funds
Since SIP is a method, the real comparison is:
SIP vs Lump Sum Investment
SIP Investment
Pros
- Reduces market timing risk
- Encourages disciplined investing
- Affordable for beginners
- Smooths volatility
Cons
- Lower returns in strong bull markets
- Requires long-term commitment
Lump Sum Investment
Pros
- Higher returns in rising markets
- Simple one-time investment
Cons
- High risk if market falls
- Requires timing skill
- Emotional stress during volatility
Which Is Better: SIP or Mutual Fund?
This question needs correction.
The real question is:
👉 Should you invest in mutual funds via SIP or lump sum?
Choose SIP If:
- You earn a monthly salary
- You want disciplined investing
- You don’t understand market timing
- You prefer lower risk over time
Choose Lump Sum If:
- You have surplus money
- Market conditions look favorable
- You can tolerate volatility
Why SIP Has Become Popular in India
SIP investments have grown rapidly in India. According to data from the Association of Mutual Funds in India (AMFI), monthly SIP contributions have crossed ₹15,000 crore in recent years.
Reasons Behind SIP Growth
- Rising financial awareness
- Easy online investing platforms
- Low entry barriers (start with ₹500)
- Increasing trust in equity markets
SIP fits perfectly with modern income patterns.
Key Benefits of Mutual Funds
1. Professional Management
Experts handle your investments.
You don’t need to track markets daily.
2. Diversification
Your money spreads across multiple assets.
This reduces risk.
3. Liquidity
Most mutual funds allow easy withdrawal.
4. Transparency
You can track performance regularly.
Regulations ensure investor protection.
Key Benefits of SIP Investment
1. Rupee Cost Averaging
You buy more units when prices are low and fewer when prices are high.
This reduces your average cost over time.
2. Power of Compounding
Compounding works best with consistent investments.
The earlier you start, the more you gain.
3. Financial Discipline
SIP forces you to invest regularly.
No guessing. No emotional decisions.
4. Lower Risk Over Time
SIP spreads your investment across market cycles.
This reduces the impact of volatility.
Summary:
Common Myths About SIP and Mutual Funds
Myth 1: SIP is a Different Product
Wrong.
SIP is just a method of investing in mutual funds.
Myth 2: SIP Guarantees Returns
No investment guarantees returns (except fixed-income instruments).
SIP reduces risk, but does not eliminate it.
Myth 3: Mutual Funds Are Only for Experts
Not true.
Beginners can start with simple index funds.
Myth 4: Lump Sum Always Gives Better Returns
Only if market timing is perfect—which is rare.
How to Choose the Right Mutual Fund for SIP
Choosing the right fund matters more than choosing SIP vs lump sum.
Factors to Consider
1. Investment Goal
- Short-term → Debt fund
- Long-term → Equity fund
2. Risk Tolerance
- Low → Conservative funds
- High → Equity funds
3. Fund Performance
Check long-term returns (5–10 years).
4. Expense Ratio
Lower costs improve returns.
5. Fund Manager Track Record
Consistency matters more than short-term gains.
Taxation on Mutual Funds in India
Understanding tax rules helps you plan better.
Equity Mutual Funds
- Short Term: 20%
- Long Term: 12.5%
(above ₹1.25 lakh gains)
Debt Mutual Funds
- Taxed as per income slab (as per recent rules)
Always check updated tax rules before investing.
Frequently Asked Questions(FAQs)
Related Links:
Final Verdict: What Should You Do?
If you’re still confused, here’s a simple answer:
👉 Start a SIP in a good mutual fund.
This approach works for most people because:
- It removes guesswork
- Builds long-term wealth
- Fits regular income patterns
If you have extra money, you can combine SIP with lump sum investing.
For more help in choosing Mutual Fund for Investment, contact Mr. Kirit Nagda, AMFI Registered Mutual Fund Distributor at kirit@arthnivesh.in or +91-9820818367.